India’s GLP-1 market enters stabilisation phase as injectables gain ground
September 08, 2026 | Tuesday | News | By Narayan Kulkarni
Injectable GLP-1 therapies are gaining preference over oral formulations
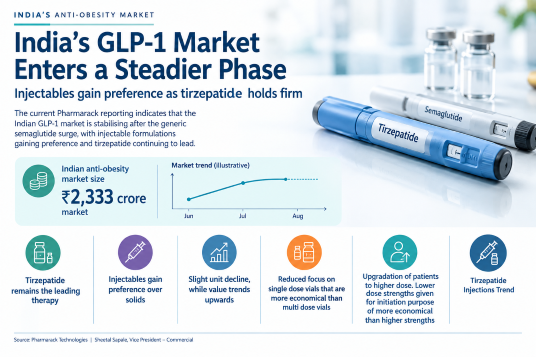
India’s rapidly expanding anti-obesity market appears to be entering a more stable phase in August 2026, following the sharp increase in consumption witnessed after the launch of generic semaglutide. According to data from Pharmarack Technologies, the anti-obesity market is now valued at around Rs 2,333 crore, with tirzepatide and semaglutide together accounting for more than 95 per cent of the market.
The August data indicate a moderation in the surge in unit consumption recorded between June and July. While the market has not completely plateaued, the sharp increase seen in July was not repeated in August, pointing towards a possible period of stabilisation.
“The GLP-1 agonist market has stabilised after the initial surge post launch of generics,” said Sheetal Sapale, Vice President – Commercial, Pharmarack Technologies.
The composition of the market, however, is changing. Injectable GLP-1 therapies are gaining preference over oral formulations, with convenience and dosing frequency emerging as important factors. While oral formulations generally require daily administration, injectable therapies are typically administered once a week.
The shift is particularly evident in semaglutide. The oral semaglutide market recorded a significant decline in August, suggesting that demand is increasingly moving towards injectable formulations. The trend reflects a broader transition in the GLP-1 market as patients and prescribers increasingly favour therapies that offer greater dosing convenience.
Within the injectable segment, tirzepatide remains dominant, accounting for around 72 per cent of the injectable market, while semaglutide holds approximately 23 per cent.
The market is therefore moving beyond the initial volume expansion triggered by generic launches towards a phase where therapy preference, treatment continuation, dose escalation and product formats are likely to have a greater influence on market performance.
Pharmarack expects monthly fluctuations to continue as the patient base evolves and treatment patterns mature. The August data suggest that the initial post-generic surge may be moderating, but the underlying demand for GLP-1 therapies remains strong.
For now, the key market trend is clear: injectables are gaining ground, oral semaglutide is losing momentum, and tirzepatide continues to lead the rapidly evolving Indian anti-obesity market.
Narayan Kulkarni
Narayan.kulkarni@mmactiv.com