"Indian Ayurveda has real demand abroad and the paperwork burden falls hardest on mid-sized manufacturers"
October 26, 2026 | Monday | Views
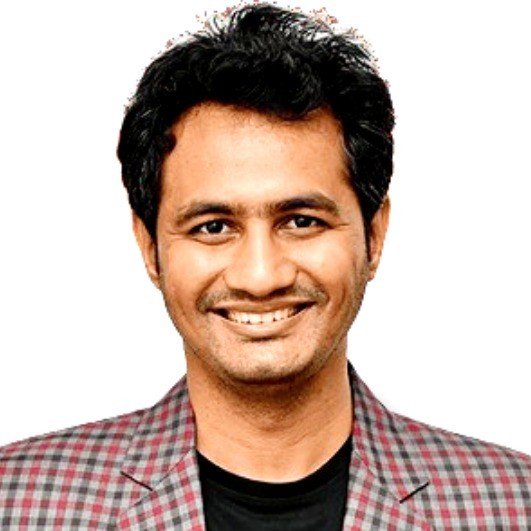
With growing consumer awareness around preventive healthcare, immunity, digestive wellness and natural health solutions, India's Ayurvedic and wellness industry is witnessing a shift from traditional remedies to everyday healthcare choices. Against this backdrop, BioSpectrum explored an exclusive interview opportunity with Aditya Mihir, Executive Director, Cura Ayurvedic & Unani Limited, focusing on how a homegrown Ayurvedic company is combining affordable healthcare, traditional formulations and business expansion to drive its next phase of growth. Founded in 1999 by Hemant Sharma, the company reported Rs 107.18 crore in FY26 revenue, compared with Rs 100.02 crore in FY24, with a net profit margin of 30%. Now, under second-generation leadership, Cura is targeting Rs 500 crore in revenue over the next three years.
What has driven Cura's growth in 2026, and how do you plan to strengthen its retail and distribution network?
Growth has come from distribution rather than marketing spend. Cura has been built over 27 years through doctors, chemists and distributors, and that network now reaches roughly 17,000 of India's 19,000 pincodes, across 28 states and eight union territories. FY2025-26 closed at Rs 107.18 crore with a net margin of 30 per cent, and the business has never taken external funding.
Strengthening it is less about adding pincodes and more about depth. Better availability at each counter, faster replenishment from our eight warehouses, and more support for the chemists and clinicians who have carried this brand. We are also building capacity ahead of demand rather than behind it.
Are you planning new product launches, investments or partnerships in the coming months?
The nearest launches sit in our Health Plus range, which is organised around areas of everyday health rather than around product formats. Cura Gut Health Plus is the first of them, and a liver formulation is in development.
The larger investment is manufacturing. We operate five units today and two more are coming, at Jewar and Guwahati, funded from operations. Jewar puts us beside the new airport and the logistics corridor forming around it. Guwahati puts capacity closer to the Northeast, which our distribution has historically served from too far away.
How will Cura's entry into D2C, e-commerce and quick commerce shape its growth strategy in 2027 and beyond?
It changes who we can reach, not what we sell. For 27 years a customer found Cura because a doctor or a chemist put a bottle in their hand. That is a strong way to earn trust and a slow way to grow, and it leaves out everyone who never meets that chemist.
Our own website went live three months ago, we are building out Amazon and Flipkart, and quick commerce follows within three months. Together we expect those channels to contribute Rs 15 to 20 crore in their first full year.
The discipline we have set ourselves is that digital does not come at the cost of the counter. We attempted an online push some years ago and it hurt our retailers. We spent two to three years designing this one so it does not.
Cura aims to reach Rs 500 crore in revenue within three years. What are the key drivers behind this ambition?
Four, and I would rather show the arithmetic than assert the number.
Channel. Digital opens a route to customers we have never been able to reach, beginning at Rs 15 to 20 crore and compounding from there.
Capacity. Five plants today, two more coming. Growth of this order is not possible without making more, and we are building ahead of the demand rather than after it.
Category. We have 600 live SKUs and work with more than 190 herb varieties. Organising them around areas of health rather than around product lines gives us a considerably larger addressable base than a juice portfolio.
The base itself. A business at Rs 107 crore running a 30 per cent net margin funds its own expansion. We are not looking for investors, which means every rupee of this has to be earned rather than bought.
It is an ambitious number. We are saying it publicly because we would rather be measured against it than describe it privately.
What are the biggest growth opportunities and challenges in India's Ayurvedic wellness market?
The opportunity is that Indians are increasingly looking after their health rather than only treating it, and Ayurveda sits naturally in that shift.
The challenge is what the category is doing to itself. Claims have inflated to the point where the boldest one wins the shelf, and standards vary so widely that a consumer has no reliable way to tell one bottle from another. Readers of this publication know what that looks like in pharma, and what it took to correct.
We have taken the opposite position and it is commercially inconvenient. Our juices are brewed for 48 hours rather than reconstituted from extracts, which is slower and costs more. Every batch goes through at least four quality tests, and up to seven depending on the formulation, at a certified NABL lab. Our formulations are patented. And we hold every claim to what we can substantiate and what the regulation permits, which routinely costs us the bolder line on the pack.
The brand that wins the shelf on the boldest claim is rarely the one still on it in ten years.
Are there any major expectations from the government to strengthen the Ayurveda healthcare market in India?
Three, and none of them is money.
Standardised testing norms for Ayurvedic manufacturing, enforced consistently. At present a manufacturer who tests thoroughly carries a cost disadvantage against one who does not, which is the wrong way round.
Clearer guidance on what a wellness product may and may not say. The current position leaves responsible manufacturers guessing and leaves everyone else room to operate. Clear lines would do more for this category than any subsidy.
Support on export certification. Indian Ayurveda has real demand abroad and the paperwork burden falls hardest on mid-sized manufacturers.
The Ministry of Ayush has done a great deal to bring Ayurveda into the mainstream conversation. The next step is making sure the quality bar rises alongside the visibility.